 how-to
How to Negotiate a Lower Price on a Home
Table of Contents
- Get Pre-Approved for a Mortgage Before Making an Offer
- How to Use Comparable Sales to Lower the Home Price
- Understand Seller Motivation and Market Conditions
- How to Write a Lowball Offer Letter That Gets Taken Seriously
- Negotiating Home Repairs After Inspection
- Counter-Offer Strategy and Closing Cost Negotiations
- Common Mistakes to Avoid When Negotiating Home Prices
- Conclusion
- Frequently Asked Questions
Last Updated: September 3, 2026
Get Pre-Approved for a Mortgage Before Making an Offer
Getting pre-approved for a mortgage is your first strategic move when learning how to negotiate a lower price on a home. Sellers take pre-approved buyers seriously because they know you can actually close the deal. Without pre-approval, your offer carries less weight, even if you promise to pay more.
Pre-approval means a lender has verified your financial situation, checked your credit, and committed to lending you a specific amount. This is different from a pre-qualification, which is just a rough estimate. During pre-approval, the lender reviews your income, employment history, credit score, assets, and debts, pulling your credit report and verifying bank statements. This process typically takes 3-5 business days and results in a letter stating your maximum loan amount and estimated interest rate (consumerfinance.gov).
A pre-approved buyer negotiates from strength. You've already secured financing, so the seller knows you can move fast and close the deal. In competitive markets, this advantage alone can determine whether your offer gets taken seriously.
How to Use Comparable Sales to Lower the Home Price
Comparable sales, or "comps," are recently sold homes similar to the one you're buying. Using comps effectively is one of the most powerful ways to negotiate a lower price because you're backing your offer with market data, not emotion.
To find comps, look for homes in the same neighborhood sold within the last 90 days that are similar in size, condition, age, and features (realtor.org). If a home sold for $385,000 three months ago with the same square footage and lot size as the property you're interested in, and the listing price is $420,000, that $35,000 difference is your negotiating leverage.
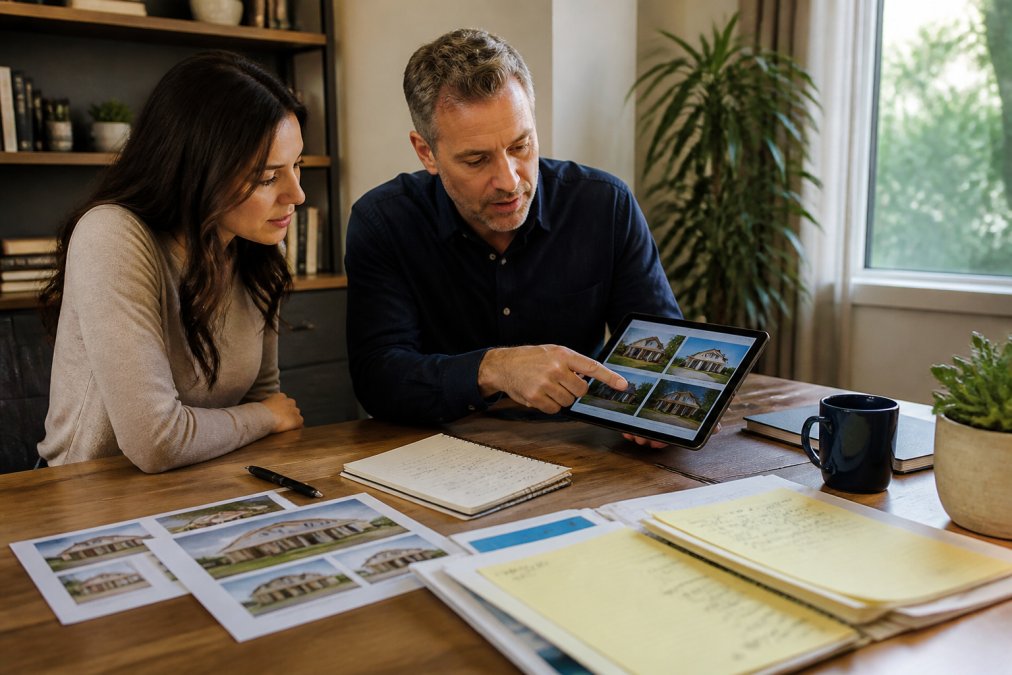
Work with your real estate agent to pull this data from the Multiple Listing Service (MLS), which shows sold prices, not just listing prices. A home listed at $450,000 that sold for $410,000 tells you the market is softer than the list price suggests. Create a spreadsheet listing each comparable home's address, sale date, sale price, square footage, lot size, condition, and key features. Calculate the price per square foot for each comp. If comps in the area average $185 per square foot and the home you're buying is listed at $200 per square foot, you have concrete evidence the price is above market.
Present this analysis to the seller through your agent, framing it as "the market data suggests an adjustment to the asking price." Motivated sellers often respond well to comps because they want to sell.
Understand Seller Motivation and Market Conditions
Understanding why a seller is selling and what the current market looks like transforms your negotiation strategy. In a seller's market (more buyers than homes), homes sell quickly and prices rise. In a buyer's market (more homes than buyers), homes sit longer and prices soften.
Look at days on market for comparable homes. If homes are selling in 10-15 days, it's a seller's market. If homes are sitting 45-60 days or longer, it's a buyer's market. This affects how aggressive your negotiation can be.
Research the specific seller's motivation. Has the home been listed for 120 days? That's a sign of motivation. Is there evidence of a job relocation or divorce? These create urgency. Did the owner list with a new agent after three months with another agent? That suggests frustration.
When you understand market conditions and seller motivation, you can tailor your offer strategy. In a buyer's market with a motivated seller, a lower initial offer makes sense. In a seller's market with a confident seller, make a strong offer with strategic contingencies you can negotiate away later.
How to Write a Lowball Offer Letter That Gets Taken Seriously
A lowball offer that's too far from market value gets rejected instantly. An offer that's just below market with solid reasoning gets consideration.
Start by determining your target price using your comps analysis. If the home is listed at $420,000 and comps average $395,000, your target might be $398,000, a 5% reduction from asking price, justified by market data. An offer at $360,000 (14% below asking) looks like you're not serious.
Structure your offer letter with three components: the offer itself, your reasoning, and your terms. State the price clearly, include the earnest money deposit amount (typically 1-3% of the purchase price), and propose a closing date (60-90 days is standard). Reference comparable sales in your reasoning: "Based on comparable sales in the neighborhood, we believe a price of $398,000 reflects fair market value." Keep it factual. Sellers respond better to logic than emotional appeals.
Include standard contingencies: a home inspection contingency, an appraisal contingency (protects you if the home appraises below your offer price), and a financing contingency. These are normal, but they do give the seller reason to reject your offer if they have competing offers.
The tone of your letter matters. Professional and respectful beats emotional. Write: "We're prepared to close quickly and have strong financing in place" rather than "We fell in love with your home."
Negotiating Home Repairs After Inspection
The home inspection creates a second negotiation opportunity. After the inspector identifies issues, you have leverage to negotiate repairs or price reductions.
Schedule your inspection as soon as possible after the offer is accepted. Most contracts give you 7-10 days for inspection. Be present during the inspection and ask questions about severity and cost. Once you have the inspection report, decide what issues matter. Focus your negotiation on items that affect safety, functionality, or resale value.
Request a written list of repairs you want completed or a credit toward repairs at closing. Be reasonable. If the inspection found $8,000 in issues, don't ask for $15,000 in credits. Present repairs in order of severity, leading with the most serious issues. "The foundation crack requires engineering evaluation and possible repair. The roof needs replacement within two years. We're requesting $6,000 in credits to address these items."
If the seller refuses all repairs, you decide: accept the home as-is or walk. You know the home's true market value including its condition, so you can decide if the price reflects the repair costs.
Counter-Offer Strategy and Closing Cost Negotiations
When you receive a counter-offer, you have three options: accept it, counter back, or walk away. Most negotiations involve 2-3 rounds of back-and-forth before both sides agree.
When countering, move your offer closer to their price, but not all the way. If you offered $398,000 and they countered at $410,000, your next offer might be $402,000. This shows you're negotiating in good faith while still pushing for your target. Include reasoning: "Based on the inspection findings and comparable sales, we believe $402,000 reflects fair value for this property in its current condition."
Closing costs typically run 2-5% of the purchase price and include lender fees, title insurance, appraisal fees, and attorney fees (consumerfinance.gov). Ask the seller to cover part of your closing costs. You might request 2-3% of the purchase price in seller concessions. Frame it as: "We're requesting the seller contribute $8,000 toward closing costs, bringing the effective purchase price to $390,000."
Common Mistakes to Avoid When Negotiating Home Prices
First-time buyers often make predictable errors that weaken their negotiating position.
Never make an offer without pre-approval, you're negotiating blind. Don't offer too low initially and damage credibility; make your first offer reasonable (within 5-10% of asking, backed by comps). Never reveal your maximum budget to the seller, listing agent, or even your agent. Negotiate analytically with data, not emotionally. Minimize contingencies or offer a higher price to compensate. Read market conditions before making your offer. Always work through agents, not directly with the seller. Give the negotiation process time; most deals reach agreement after 2-3 rounds.
Conclusion
Learning how to negotiate a lower price on a home requires preparation, data, and psychology. Start with pre-approval to establish credibility. Use comparable sales to anchor your negotiation in market reality. Understand what's driving the seller and what market conditions you're in. Make your initial offer reasonable but backed by analysis. Use the inspection to identify legitimate negotiation points. Counter strategically, moving your offer incrementally toward the seller's position.
At Bernie Krause, we guide buyers through this entire process with expertise in the East Valley market. Whether you're a first-time buyer or relocating to Arizona, having an experienced agent who understands local market conditions, knows the neighborhoods, and can provide expert guidance makes the difference between overpaying and getting fair value. Ready to start your home buying journey with confidence? Reach out to Bernie Krause to discuss your next home purchase and learn how local market expertise translates to real savings.
Frequently Asked Questions
Q: How much can you usually negotiate a home price down?
A: The amount you can negotiate depends on market conditions, the property's condition, and seller motivation. In a buyer's market, you may negotiate 5-10% or more off the asking price. In a seller's market, reductions are typically 1-3%. A home inspection often reveals repairs that justify larger price reductions. Your real estate agent can analyze comparable sales to determine realistic negotiation range for your specific property.
Q: What should I include in a lowball offer letter to make it credible?
A: A credible lowball offer includes: proof of mortgage pre-approval, comparable sales data supporting your price, a detailed explanation of needed repairs with inspection estimates, a reasonable closing timeline, and earnest money showing serious intent. Avoid insulting language or vague justifications. Instead, present your offer as data-driven and backed by market analysis. Include contingencies that protect you but don't complicate the seller's exit.
Q: How do I use comparable sales to justify a lower offer?
A: Gather 3-5 recently sold homes similar to your target property in size, condition, location, and age. Compare sale prices per square foot and note any differences in features or needed repairs. Present this data clearly in your offer, highlighting how your target home's condition or market position justifies a lower price than recent comps. Your agent can pull official MLS data to strengthen this argument and make it harder for the seller to dismiss.
Q: What repairs should I ask for after a home inspection?
A: Request repairs for structural issues, major system failures (roof, HVAC, plumbing, electrical), and code violations. For cosmetic or minor wear, ask for repair credits instead so you can choose contractors. Get contractor estimates for major items to quantify your request. Prioritize health and safety issues over aesthetic concerns. Be realistic: sellers often counter with partial credits or refuse minor requests, so focus negotiation leverage on items that affect the home's value or livability.
This article was written using GrandRanker